

Iridium IR Brief No. 471 - What's Next for GCC Markets - 25 October 2026
The Week Ahead
Regional markets – Iran threatens undersea cables as 36 companies host earnings calls
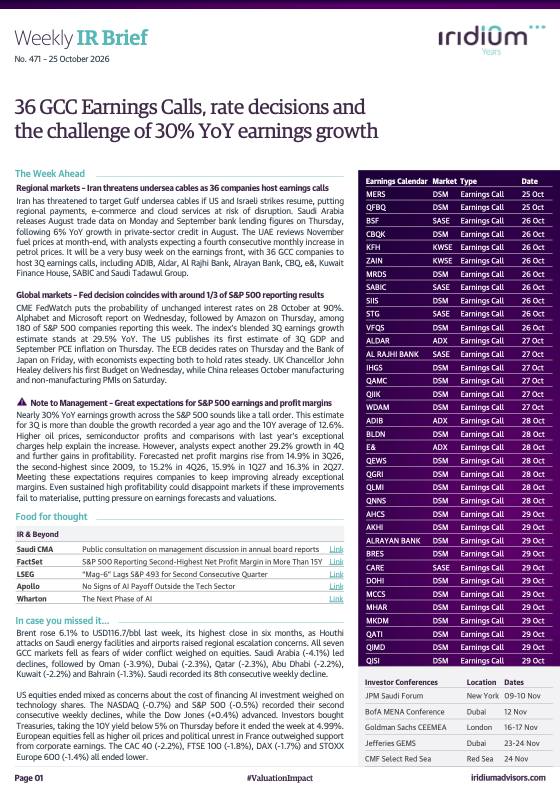
Iran has threatened to target Gulf undersea cables if US and Israeli strikes resume, putting regional payments, e-commerce and cloud services at risk of disruption. Saudi Arabia releases August trade data on Monday and September bank lending figures on Thursday, following 6% YoY growth in private-sector credit in August. The UAE reviews November fuel prices at month-end, with analysts expecting a fourth consecutive monthly increase in petrol prices. It will be a very busy week on the earnings front, with 36 GCC companies to host 3Q earnings calls, including ADIB, Aldar, Al Rajhi Bank, Alrayan Bank, BSF, CBQ, e&, Kuwait Finance House, SABIC and Saudi Tadawul Group.
Global markets – Fed decision coincides with around 1/3 of S&P 500 reporting results
CME FedWatch puts the probability of unchanged interest rates on 28 October at 90%. Alphabet and Microsoft report on Wednesday, followed by Amazon on Thursday, among 180 of S&P 500 companies reporting this week. The index’s blended 3Q earnings growth estimate stands at 29.5% YoY. The US publishes its first estimate of 3Q GDP and September PCE inflation on Thursday. The ECB decides rates on Thursday and the Bank of Japan on Friday, with economists expecting both to hold rates steady. UK Chancellor John Healey delivers his first Budget on Wednesday, while China releases October manufacturing and non-manufacturing PMIs on Saturday.
Note to Management – Great expectations for S&P 500 earnings and profit margins
Nearly 30% YoY earnings growth across the S&P 500 sounds like a tall order. This estimate for 3Q is more than double the growth recorded a year ago and the 10Y average of 12.6%. Higher oil prices, semiconductor profits and comparisons with last year’s exceptional charges help explain the increase. However, analysts expect another 29.2% growth in 4Q and further gains in profitability. Forecasted net profit margins rise from 14.9% in 3Q26, the second-highest since 2009, to 15.2% in 4Q26, 15.9% in 1Q27 and 16.3% in 2Q27. Meeting these expectations requires companies to keep improving already exceptional margins. Even sustained high profitability could disappoint markets if these improvements fail to materialise, putting pressure on earnings forecasts and valuations.
More on Investor Relations
Iridium IR Brief No. 470 - What's Next for GCC Markets - 18 October 2026
The Week Ahead
Regional markets – IMF detailed outlook and UAE bank earnings calls set the agenda
Egypt’s parliament meets today after President Sisi requested authority to provide military support to Saudi Arabia if Riyadh asks, following further Houthi attacks on the Kingdom. The IMF publishes its detailed regional outlook on Thursday, after forecasting a 4.8% contraction in GCC economies this year and a recovery of about 9% in 2027. That recovery assumes trade and shipping return to normal in 1Q 2027, with exports recovering by mid-year. Saudi Arabia reports 3Q real estate prices and August business activity on Tuesday, followed by September construction costs on Thursday. Ahlibank (Qatar), Commercial Bank of Dubai, Dubai Islamic Bank, Emirates NBD, Ezdan Holding, Gulf Warehousing, Medicare Group, Nakilat, and Qatari Investors Group will host 3Q earnings calls this week.
Global markets – Meta’s 3Q results test AI spending as growth and inflation data arrive
Markets will look to Meta’s results on Wednesday for evidence that earnings can keep pace with AI capex, following last week’s technology sell-off. Netflix reports on Tuesday; Tesla, IBM and Texas Instruments follow on Wednesday, with Procter & Gamble on Thursday. Analysts expect more than 30% YoY growth in S&P 500 earnings for 3Q. China publishes 3Q GDP on Monday, with economists forecasting growth of 4.4% YoY, alongside September retail sales, industrial production and investment data. The UK releases September inflation on Wednesday and retail sales on Friday. Friday also brings October flash PMIs for the US, euro area and UK, plus the final University of Michigan consumer sentiment and inflation expectations readings ahead of the Fed’s 28 October decision.
Note to Management – Explain how the company will fund its growth in 2027
CoreWeave's sell-off last week is a timely reminder for boards and management teams that growth only creates value when returns exceed the cost of capital. The AI infrastructure provider had a large contracted order book, but investors questioned the cost of funding its expansion and the returns shareholders would earn. Boards should revisit investment plans where expected returns leave little room for higher funding costs or delays. Management should explain how much capital is required to deliver its growth targets, what that capital is expected to earn and when investors can expect the cash flows.
Iridium IR Brief No. 469 - What's Next for GCC Markets - 11 October 2026
The Week Ahead
Regional markets – IMF updates GCC outlook as Qatari banks open 3Q earnings call season
This week, the IMF will update its outlook for GCC economies after warning that regional output would contract in 2026. It expects a recovery in 2027 if shipping returns to normal. On Wednesday, markets will assess whether US inflation could trigger another Fed hike, which could raise borrowing costs across the GCC. Trump has announced plans for Russia to supply more than 300Kt of diesel immediately and 500Kt in November. These shipments could ease fuel and transport costs, although Moscow has yet to confirm the volumes and timing. Saudi Arabia will report September inflation on Thursday, after the annual rate held at 1.8% for four consecutive months. We expect QNB, Dukhan Bank and QIB to host their 3Q Earnings Calls this week; QNB already reported quarterly profit of QAR4.65bn, up 4.9%.
Global markets – Major US banks report 3Q earnings ahead of September CPI
Economists expect Wednesday’s US CPI report to show headline inflation of 3.7% YoY and core inflation at 2.5%, ahead of the FOMC’s 28 October meeting. The US will publish producer prices and retail sales on Thursday. JP Morgan, Goldman Sachs, Citigroup and Wells Fargo report on Tuesday; Bank of America and Morgan Stanley follow on Wednesday. Analysts forecast around 31% YoY growth in S&P 500 earnings, with technology and major AI companies accounting for two-thirds of the increase. Investors will also look to ASML on Wednesday and TSMC on Thursday for updates on semiconductor demand and capex. China releases September trade and inflation figures on Wednesday. The UK publishes August GDP on Thursday.
Note to Management – Prepare your earnings materials for IFRS 18
Companies must apply IFRS 18 from 1 January 2027, use the new presentation for their 1Q 2027 results and restate their 2026 comparatives. The new standard defines operating profit and requires companies to explain and reconcile management-defined performance measures in their financial statements. CFOs and IR teams need to update earnings materials and provide analysts with reconciliations that explain changes to reported figures. Iridium will arrange a workshop for companies in November on IFRS 18 implications for investor relations. Email advance@iridium.ae for details.
Iridium IR Brief No. 468 - What's Next for GCC Markets - 4 October 2026
The Week Ahead
Regional markets – OPEC+, September PMIs and the start of 3Q reporting
OPEC+ meets today and is expected to keep November production targets unchanged, as Gulf oil exports remain below pre-war levels. Saudi Arabia, Pakistan and Türkiye will also hold emergency talks in Riyadh this week on whether to engage the Houthis politically, while Riyadh continues to assess military options to restore shipping through Bab el-Mandeb. With US–Iran talks still stalled, the WSJ reports that the US is sending a third aircraft carrier and up to 10,000 additional troops to the Middle East. In Abu Dhabi, AI Everything runs on Tuesday and Wednesday, bringing together global AI companies, investors and policymakers, while Moody’s Saudi Summit in Riyadh on Wednesday focuses on the Kingdom’s credit markets. Saudi Arabia and the UAE report September non-oil PMIs on Monday. Dukhan Bank and QNB kick off the GCC earnings season this week.
Global markets – Bond yields, FOMC minutes and RBI rate decision
The 10Y US Treasury begins the week near multi-decade highs after reaching 5.34%, while weaker September payrolls cut the probability of another Fed hike on 28 October to 22% from 64% a week earlier. Fed minutes from its September meeting on Wednesday University of Michigan consumer sentiment on Friday give the next reads on growth and inflation expectations. The Reserve Bank of India is expected to raise its policy rate by 25bps to 5.50% on Wednesday. German factory orders and trade data and Euro Area PPI are also due this week. Delta reports on Friday, giving a look its ability to recover fuel costs.
Note to Management 1 – Foreign investors exit USD2.3bn of GCC equities in 3Q 2026
GCC equities saw net foreign outflows of USD1.37bn in September, including USD1.16bn from Saudi Arabia. 3Q outflows reached USD2.33bn, the highest quarterly outflow in the series since 2019 (see: Foreign Flow Analysis).
Note to Management 2 – Saudi CMA earnings calls consultation; new ADX IR guidelines
Saudi’s CMA proposes mandatory twice-yearly earnings calls for Main Market companies. ADX’s IR Guide sets minimum requirements for IR officers, websites, presentations and reporting, with annual assessments and potential penalties for non-compliance.
Iridium Foreign Flow Analysis - September 2026
Foreign investors exit USD2.3bn of GCC equities in 3Q as earnings season begins
GCC equities recorded net foreign outflows of USD1.37bn in September, up from USD544mn in August. Saudi Arabia accounted for USD1.16bn of the total, its third consecutive month of outflows. Selling eased in the UAE, where outflows narrowed to USD149mn from USD351mn. Qatar attracted minor inflows of USD21mn, its second consecutive monthly inflow. 3Q 2026 outflows reached USD2.33bn, compared with inflows of USD4.80bn in 3Q 2025. This is the highest quarterly outflow in the series, which begins in 2019.
The MSCI GCC Index fell 3.5% in September, underperforming the MSCI EM Index’s 0.8% decline. Saudi Arabia (-6.1%) and Qatar (-6.0%) led the declines, while Kuwait fell 1.2%. The UAE was the only market to rise, gaining 3.3% to its highest level since February.
Key takeaway for listed companies
The Iran war has lasted longer than expected, oil prices remain high, interest rates have risen and bond yields are at multi-decade highs. As discussed in our 2Q 2026 GCC Earnings Call Sentiment report, analysts and investors will ask whether FY2026 guidance remains achievable, which assumptions have changed and what October business activity implies for 4Q and 2027 guidance.
Company leaders should also review regulatory developments. ADX’s new IR guidelines set minimum standards for a named IR officer, searchable disclosures, MD&A and investor presentations. Saudi CMA consultations cover earnings calls and the IPO process. These measures are intended to improve the long-term attractiveness of regional markets to global investors.
Sources: Bloomberg, S&P Capital IQ Pro, Stock Exchanges, Iridium Advisors
Iridium IR Brief No. 467 - What's Next for GCC Markets - 27 September 2026
The Week Ahead
Regional markets – Hormuz proposal, AFCM and MEIRA conferences
Regional markets start another week without an agreement to reopen Hormuz, after the WSJ reports that President Trump rejected Iran’s seven-day proposal. Tehran’s terms include an end to regional hostilities, the lifting of the US naval blockade and oil sanctions, and the release of frozen assets. In Abu Dhabi, the Arab Federation of Capital Markets holds its annual conference on Tuesday and Wednesday, with Arqaam Capital arranging meetings between issuers and investors. The MEIRA Annual Conference and Awards follows in Dubai on Thursday. Saudi Arabia reports 2Q unemployment and August bank lending and money supply on Wednesday.
Global markets – US jobs, inflation and a Fed hike on the horizon
US August PCE inflation on Wednesday and September payrolls on Friday lead the week. With the FOMC meeting a month away, CME FedWatch prices a 64% probability of another rate hike on 28 October. Wednesday also brings the third estimate of 2Q GDP and annual revisions to US growth and inflation data. The Reserve Bank of Australia is expected to raise its cash rate by 25bps to 4.60% on Tuesday, its fourth increase this year. Euro area September flash inflation is due on Friday, following August’s 3.2% reading. China reports September manufacturing and non-manufacturing PMIs on Wednesday, while Micron and Nike feature in the earnings calendar.
Note to Management – Saudi CMA changes to IPO disclosures and book-building
Saudi Arabia’s CMA opened a consultation on 22 September on proposed changes to IPO disclosures, book-building and underwriting. Issuers would be required to disclose “forward-looking statements and forecasts relating to the issuer, including forward-looking financial performance indicators, for a period of at least one year”, with financial advisers responsible for due diligence on these disclosures. Participation orders would be checked against investors’ available cash or cash equivalents and become binding for payment by the subscription deadline specified in the prospectus. Underwriting agreements would have to be effective before book-building, with the underwriter committed to purchasing all offered shares from the start of that process. The consultation closes on 22 October, with implementation scheduled for 2 November, subject to final approval.
Iridium IR Brief No. 466 - What's Next for GCC Markets - 20 September 2026
The Week Ahead
Regional markets – Trump-GCC meeting and EFG Hermes London Conference
President Trump is scheduled to meet GCC leaders in New York on Tuesday on the sidelines of the UN General Assembly to discuss the Iran war and US plans for the period that follows. Iranian President Masoud Pezeshkian and Foreign Minister Abbas Araqchi will also attend after Washington granted visas to the Iranian delegation. The meeting comes after further Houthi attacks on Saudi infrastructure and continued disruption to regional oil routes. From Monday to Thursday, the EFG Hermes London Conference brings together MENA-listed companies and international institutional investors at Emirates stadium. Saudi markets will be closed on Wednesday for National Day.
Global markets – Trump-Xi summit and the next Fed hike
President Trump hosts Xi Jinping at the White House on Thursday for their second meeting this year and Xi’s first US state visit in a decade. Trade, tariffs, rare earths, AI, Taiwan and Iran are all on the agenda, with markets watching whether the leaders extend the tariff truce due to expire in November. Attention will also stay on the Fed after last week’s first rate hike since 2023. Sixteen of 18 policymakers now expect at least one further hike this year, making this week’s Fed speeches and Wednesday’s US flash PMIs the first read on how quickly another hike could come (CME FedWatch: 58% probability of a 25bp hike on 28 October). Switzerland, Sweden, Norway, South Africa, Mexico and Indonesia also decide interest rates this week.
Note to Management – 96% of institutional investors already use AI
BNY surveyed 50 institutional investors representing $3.8tn of AUM to understand how investors generate ideas, choose between companies, use AI and respond to market volatility. Investors still start with company-specific factors such as business quality, management credibility, capital allocation and valuation, but AI is already embedded in the research process. 84% of respondents use AI and another 12% are piloting it, mainly for information gathering, summarising filings and earnings calls, and comparing companies. Management quality remains the highest-rated qualitative factor at 4.3/5, followed by management credibility and track record at 4.1/5.
Iridium IR Brief No. 465 - What's Next for GCC Markets - 13 September 2026
The Week Ahead
Regional markets – Salalah talks on Hormuz and new US sanctions on unnamed bank
Iran and Gulf states will meet in Salalah on Monday to discuss regional security and the Iran-Oman proposals for safe commercial shipping through the Strait of Hormuz. The talks will focus on a temporary arrangement for managing commercial traffic through the Strait, although Iran has said no deal will be signed. The meeting follows renewed attacks on vessels, Houthi advances around Bab el-Mandeb and a drone attack that temporarily shut Saudi Arabia’s East-West oil pipeline. Also on Monday, US Treasury Secretary Scott Bessent says Washington will sanction another large, unnamed bank as it increases financial pressure on Iran. Saudi Arabia reports August CPI and wholesale prices on Tuesday.
Global markets – Fed, BoJ and BoE rate decisions
The Fed meets on Wednesday with CME FedWatch pricing an 87% probability of a 25bp rate hike, which would be the first increase since July 2023. August inflation, stronger payrolls and Brent above $100 pushed US rate expectations higher last week, while the 10-year Treasury yield briefly reached 4.99%. The Bank of Japan is expected to raise its policy rate by 25bps to 1.25% on Friday, the highest level in 31 years and its second hike in three months. The Bank of England is expected to hold at 3.75% on Thursday after July GDP rose 0.4% MoM, compared with expectations for no growth. China reports August industrial production, retail sales and fixed asset investment on Tuesday.
Note to Management – OpenAI launches ChatGPT for Financial Services
OpenAI launched ChatGPT for Financial Services this week, a new version of ChatGPT Work built around GPT-6 Astra and financial data from Daloopa, PitchBook and LSEG News. Developed with Morgan Stanley and Evercore, the product initially focuses on investment banking and equity research. It can research companies, analyse earnings, compare peers, build financial models and prepare research notes and other client materials. Initial workflows include valuation analysis, LBO modelling, buyer screening, earnings analysis and pitchbook preparation. Morgan Stanley plans to use it for company research and analysis, while Evercore says it will use it to work through client inquiries.
Iridium IR Brief No. 464 - What's Next for GCC Markets - 06 September 2026
The Week Ahead
Regional markets – OPEC+ meeting, Saudi GDP and UAE PMI
OPEC+ meets today and is expected to keep October output unchanged. Iran-related uncertainty continues after Iran fired ballistic missiles at two US Navy ships and the US struck three Iranian oil tankers, including one near Kharg Islands. In Saudi Arabia, final 2Q GDP is due on Tuesday and July industrial production on Thursday. UAE markets will also digest last week’s stronger August PMI, which rose to 55.3 from 52.7 in July. Oman reports August inflation on Thursday, with the annual rate expected to rise to 3.5% from 3.2%.
Global markets – US inflation, ECB rates and software earnings
US inflation will dominate market headlines next week, with August PPI on Thursday and CPI on Friday, the final major data releases before the Fed’s 16 September meeting. Headline CPI is expected to rise 0.4% MoM, up from 0.1% in July, while core CPI is forecast at 0.2%; headline and core PPI are both expected to rise 0.3%. The ECB meets on Thursday and is widely expected to raise its deposit rate by 25bps to 2.50%. China reports August trade data on Tuesday and CPI on Wednesday, with inflation expected to rise to 0.9% from 0.5%, while UK July GDP is due on Friday and is expected to be flat. Oracle and Adobe report results on Thursday.
Note to Management 1 – Earnings call sentiment rebounds despite Iran war
The Iridium GCC Earnings Call Sentiment Index rose 17% to 34.5 points for 2Q 2026 earnings calls held in July and August, its first increase since the Iran war began. Our Iridium Quant Lens analysis of 150 earnings calls also shows that analyst and investor Q&As focused almost entirely on 2H 2026 performance, challenging whether the growth implied by FY2026 guidance is still achievable with less than four months to go.
Note to Management 2 – Foreign investor outflows widened in August 2026
Our Foreign Flow Analysis shows that GCC equities saw $544mn of outflows in August vs USD415mn in July. The UAE accounted for $351mn, Saudi Arabia for $202mn. Kuwait posted a sixth consecutive monthly outflow, although narrowing to $37mn. Qatar attracted $62mn, its first net inflow since February. QTD outflows have reached $1bn.
Iridium Foreign Flow Analysis - August 2026
Foreign investor outflows widen in August as GCC issuers enter corporate access season
Net foreign outflows from GCC equities increased to USD544mn in August, vs USD415mn in July. The UAE accounted for USD351mn, while Saudi Arabia recorded USD202mn. Kuwait posted a sixth consecutive monthly outflow, although it narrowed to USD37mn. Qatar attracted USD62mn, its first net inflow since February. 3Q-to-date outflows have reached USD1.0bn.
The MSCI GCC Index rose 3.9% in August, its best month since January, outperforming the MSCI EM Index’s 3.2% gain for a second consecutive month. MSCI Saudi Arabia (+5.3%) led despite foreign outflows, followed by the UAE (+1.6%) and Kuwait (+0.3%). Qatar fell -0.6%. The MSCI GCC index enters the autumn conference season up 3.2% YTD, compared to 22.4% for MSCI EM.
How can GCC companies respond to foreign investor outflows?
GCC companies should use the autumn investor conference season to meet recent sellers, understand why they reduced their holdings and address questions left unanswered in 2Q earnings calls. Our GCC Earnings Call Sentiment report found that analysts focused on FY2026 guidance, sources of growth and capital allocation. Companies should prepare to discuss these topics, supported by post-quarter performance data and any changes to the 3Q outlook.
The conference calendar begins on 3 September with CMF Select in Shanghai. Citi GEMs and UBS GEMs conferences follow in New York, then J.P. Morgan EM/FM and EFG Hermes MENA in London. Regional 1x1 events include HSBC MENAT and Jefferies GEMs conferences in Dubai. As regional events remain at risk of cancellation, companies should attend at least one international conference or arrange a non-deal roadshow to avoid any prolonged gap in investor meetings.
Sources: Bloomberg, S&P Capital IQ Pro, Stock Exchanges, Iridium Advisors
Iridium Quant Lens: 2Q 2026 GCC Earnings Call Sentiment
Iridium Quant Lens - 2Q 2026 Earnings Call Sentiment Analysis
GCC earnings sentiment rebounds 17% despite Iran war
The Iridium GCC Earnings Call Sentiment Index rose 17% to 34.5 points for 150 second quarter 2026 earnings calls held in July and August, its first increase since the Iran war began. Iridium Quant Lens NLP now covers more than 15 million words across 3,200+ GCC earnings call transcripts from companies representing over 70% of total market capitalisation.
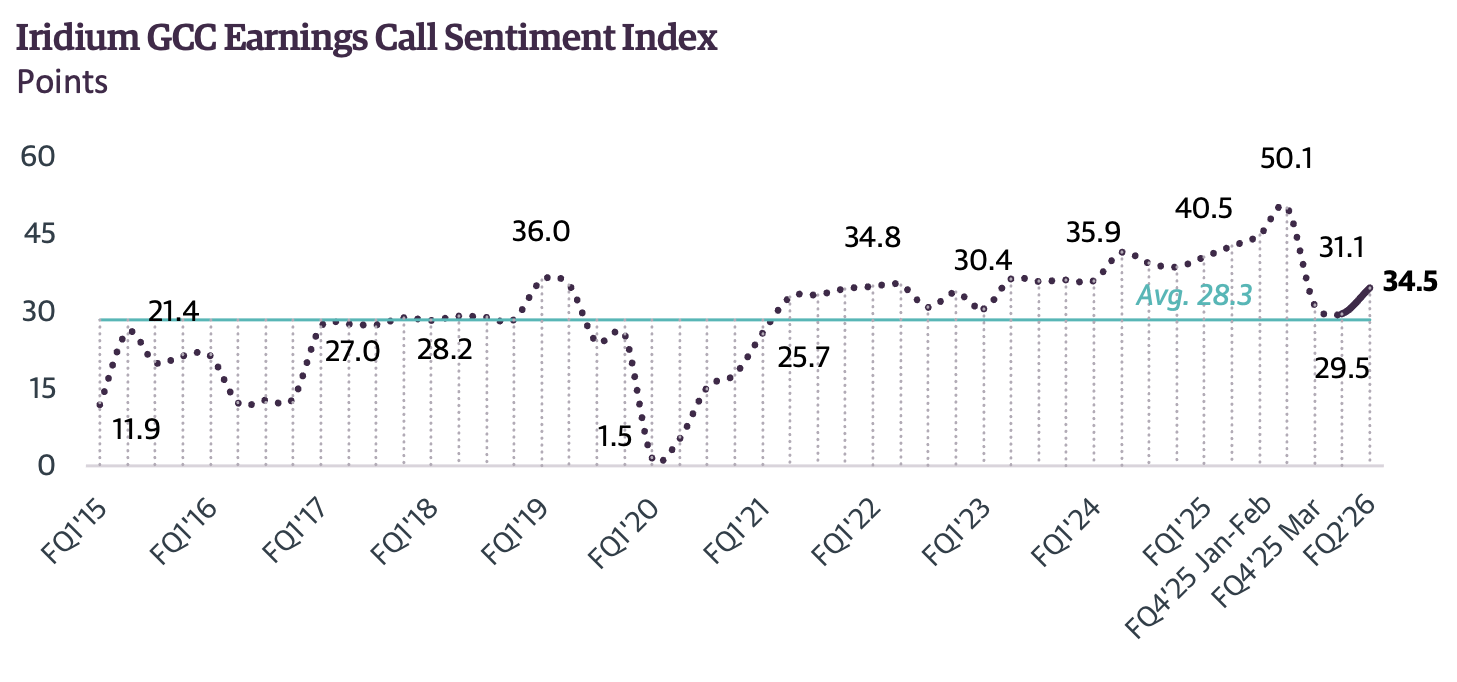
The improvement was concentrated in management presentations, where sentiment rose 15% to 45.7 points, above its long-term average of 39.8. Q&A sentiment increased 9% to 12.9 points but remained well below its long-term average of 15.8, widening the Sentiment Bias for a second consecutive quarter to 32.7 points. Analyst Q&As focused almost entirely on 2H 2026, challenging whether the growth implied by FY2026 guidance was achievable.
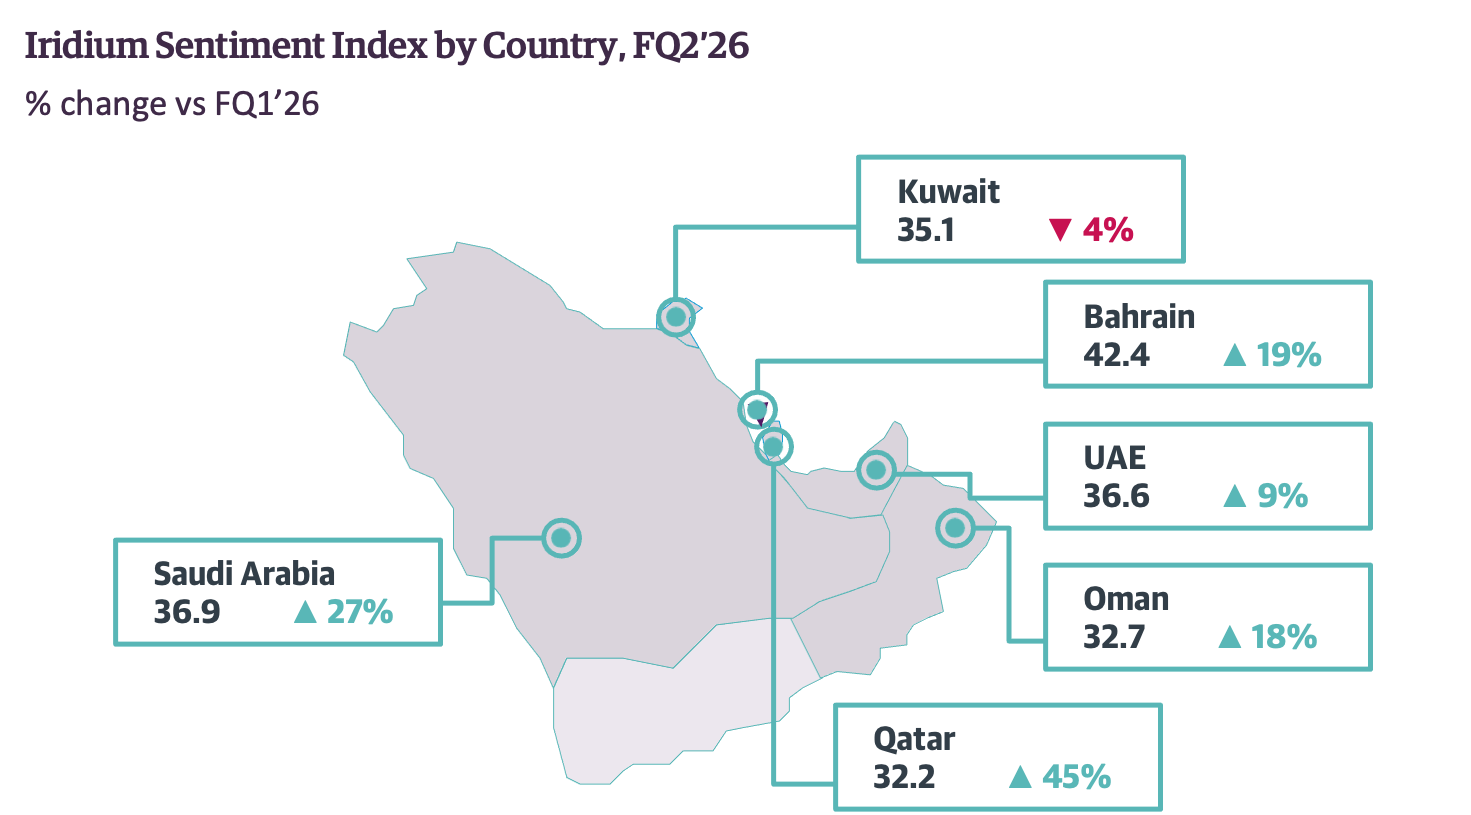
Sentiment increased in five of the six GCC countries. Qatar (+45%) and Saudi Arabia (+27%) recorded the largest gains, followed by Bahrain (+19%), Oman (+18%) and the UAE (+9%), while Kuwait (-4%) was the only market to decline. For the first time since the conflict began, all six markets were above their long-term averages.
The share of companies beating consensus eased to 64% from 68% in the previous quarter but remained well above the 54% recorded in 4Q 2025. Reported earnings continued to exceed expectations through a second disrupted quarter.
Key Themes & Takeaways
Management reported 2Q but analysts asked about 2H
Management presentations shifted from reporting the immediate disruption to quantifying the recovery. Effects that could not be measured in April and May were quantifiable by July and August, although some companies stopped referring to the conflict even as others reported renewed escalation. Analysts focused almost entirely on 2H 2026, requesting post-quarter trading data on nearly every call and challenging whether the growth required to meet FY2026 guidance was achievable.
Management explained reported performance but offered little on year-end outlook. Questions about the duration of the disruption and timing of normalisation rarely received firm answers. One analyst asked to put the disruption on a scale: “So, if 10 was, for example, as bad as it got and 0 is 100% normal, where are we now,…how long before we get back to 0 or 1?” The CEO replied that “you read the newspapers as well as we do”, described the Strait of Hormuz as “checkered at best” and said that “this is the new normal, and business-as-usual approach with the alternatives”. The CEO’s response was typical of the quarter. Companies could increasingly quantify the disruption, but the course of the conflict provided no reliable basis for forecasting when conditions would normalise.
Key insights from 2Q 2026 Earnings Calls
- Macro environment and consumer demand: Demand improved through the quarter across most consumer companies and domestic markets, with several returning to growth by June. Some weakness pre-dated the war. Jamjoom Pharma said that “the market correction began before the geopolitical developments”, separating softer Saudi consumer demand from the regional disruption.
- Pricing, margins and costs: Most companies passed through higher freight, insurance and fuel costs, limiting near-term margin pressure. Analysts asked how much of the increase would remain as trading conditions normalised. War-risk premiums remained elevated. Milaha cited war-risk insurance and crew allowances, while Spinneys reported container freight rising from $3,000 to $17,000 before declining to around $7,000.
- Balance sheet, funding and credit quality: Burjeel returned to the sukuk market after deferring its March issue. The $500 million transaction was more than three times covered, with 61% allocated to international investors. TAQA issued the largest blue bond in EMEA and repaid the precautionary facility drawn at the start of the conflict. Bank commentary was mixed. Gulf Bank cut its cost-of-risk guidance, while Dukhan Bank continued to build provisions and withheld its interim dividend to retain liquidity buffers.
- Capital allocation, investment and project pipelines: Capital commitments increased despite the continuing conflict. The previous quarter centred on maintaining existing capex plans and deferring capital markets transactions; 2Q included several new commitments. Jazeera Airways bought eight aircraft and began retrofitting its fleet during the airport shutdown, while DP World committed around $750 million to additional terminal capacity in Fujairah following the disruption at Jebel Ali.
- Technology, digital transformation and AI adoption: AI disclosures became more detailed, with companies quantifying adoption and operating impact. Saudi National Bank outlined an enterprise AI programme with its own operating model and governance. Alamar reported that AI handled around 70% of customer-service interactions and reduced resolution times by more than three-quarters.
Select Sector Observations
- Real estate and construction: The sector recorded the highest sentiment score at 44.6 points, supported by construction order books and pricing despite weaker real estate transaction volumes. Orascom Construction increased its backlog 13.9% to $10.9 billion, driven by US awards, although supply into eastern Saudi Arabia and the UAE remained disrupted, while Dar Al Arkan described Saudi transaction volumes as “one of the lowest in the recent history”.
- Energy and commodities: Aramco reported Hormuz flows at around 10% of pre-conflict volumes and said the impact would extend into 2027, but retained its $50-55 billion capex guidance. SABIC reported volumes down 33% and prices up 41%, while Borouge reported physical damage to its facilities and lower utilisation, and said it was “not in a position to really predict the Q3 outcome”.
- Financials: Bank profitability remained resilient, although the effects of the conflict were evident in payment deferrals and dividend decisions. QNB disclosed QAR 480 million of deferred instalments and adopted an annual dividend, while several banks withheld interim payouts as relief measures in Qatar and the UAE approached their end-September expiry. NBK declined to give earnings or capital adequacy guidance, saying it “would not be prudent” under current conditions.
- Shipping and logistics: The war’s impact varied by business model, with DP World operating Jebel Ali at around 10% of normal throughput and committing approximately $750 million to two new terminals in Fujairah, while ADNOC L&S raised guidance for the third time despite reporting that vessels “continue to be targeted while transiting the Strait of Hormuz”.
- Travel, leisure, hospitality: Volumes remained below prior-year levels, while pricing and ancillary revenue supported earnings. Jazeera Airways carried 40.6% fewer passengers but increased ancillary revenue 78%. Both Jazeera and Flynas restored capacity towards prior-year levels in July. Jabal Omar offset first-quarter weakness by focusing on domestic pilgrims.
Looking Ahead to 3Q 2026 Earnings Calls
The 3Q earnings cycle will show whether the improvement reported in 2Q continued through the summer. With 9M reported, analysts will compare YTD performance and October data with the outlook management described in 2Q. Companies that provide formal guidance will also be asked whether it remains achievable.
For banks, the expiry of relief measures will provide the first evidence of how borrowers with deferred payments are performing, although arrears, loan staging and provisions may react with a time lag. In other sectors, analysts are likely to examine whether conflict-related pricing is falling while freight and insurance costs remain high. Companies that withdrew guidance will also be asked when it can be restored. Analysts will also begin to ask what current trading and cost levels imply for 2027.
Management implications
- Use the management presentation to cover the likely questions. In more than 50% of 2Q calls, analysts raised issues management had not covered. The presentation should include current trading, FY2026 guidance, margins and costs rather than leaving these subjects to the Q&A.
- Explain the outlook for 4Q. Companies with formal guidance should say whether it remains achievable and identify any changed assumptions. Others should explain which trends reported in 3Q are continuing into 4Q.
- Provide post-quarter trading data. Analysts asked for July and August data during the 2Q earnings cycle. In 3Q, they will want October and early November figures.
Common Analyst Questions
What analysts were asking in July and August
1. 2H 2026 guidance
- Your guidance implies an acceleration in the second half – what leading indicators support it?
- What are you seeing in July and August, and is the quarter tracking against that assumption?
- What does your guidance assume about the timing of normalisation, and what happens if there are delays?
2. Margins, pricing and cost base
- Which of the cost increases absorbed this quarter are structural, and which unwind when conditions normalise?
- How much pricing headroom is left, and what happens to margins if volumes recover while prices soften?
- War risk and insurance premiums have not receded – what have you assumed for the rest of the year?
3. One-offs, windfalls and run-rate
- How much of this quarter's result is attributable to one-offs or conflict-related gains/ losses?
- What is the normalised run-rate excluding those items?
- If conditions normalise, how much of the current pricing advantage do you retain?
4. Provisioning, deferrals and credit quality
- Why did you reverse part of the additional provision taken in Q1, and what would lead you to increase provisions again?
- What is the size of your deferred loan book, and how do you expect it to perform once the relief programme ends?
- Coverage ratios fell this quarter while non-performing loans were stable – what drove that?
5. Capital allocation, dividends and investment
- What changed in your assessment to justify committing capital at this point in the cycle?
- Why was the interim dividend withheld, and what conditions would restore it?
- Are you seeing valuation resets or distressed assets that change your acquisition appetite?
Iridium IR Brief No. 463 - What's Next for GCC Markets - 30 August 2026
The Week Ahead
Regional markets – MSCI index rebalancing and questions on sanctions exposure
This week, MSCI’s August index rebalancing takes effect after Monday’s close. Saudi and UAE August PMIs on Thursday will provide a read on non-oil activity. Markets will also assess whether the US Treasury’s action against Banque Misr has broader implications. There is currently no indication that any GCC banks are being targeted, but the action could revive investor questions around potential sanctions exposure, counterparties and payment channels. Iran’s statement on Friday that restrictions in the Strait of Hormuz will remain in place until US military action ends gives little hope for a near-term normalisation in shipping. The earnings calendar is very light, with a maiden earnings call from Oman India Fertiliser Company, which listed in July after an 18x-oversubscribed IPO at a market value of $2.7bn.
Global markets – US jobs, Fed rate hike probability and cloud earnings
Kevin Warsh’s Jackson Hole speech put rate hikes firmly back on the table this week. The probability of a September hike rose to 56% from 35% a day earlier, while markets now price an 89% chance of at least one hike December 2026 and a 51% probability of two or more. This coming Friday’s US jobs report will now carry more weight, with payrolls expected to rise by 45K in August and unemployment forecast at 4.2%. Broadcom, Dell, Palo Alto Networks and Snowflake earnings will show whether enterprise technology and cloud spending remain intact. In Europe, Euro Area inflation is expected to rise to 3.2%, while China’s August PMIs, India GDP and Australia GDP are on the Asian calendar.
Note to Management – MSCI August Index changes will be implemented on 31 August
MSCI’s August review makes seven GCC changes in the Global Standard indexes (see chart) and 16 in the Global Small Cap indexes. Saudi Arabia’s Al Mouwasat Medical Services, Bank AlJazira, Saudi Logistics Services, Saudi Tadawul Group, solutions and Qatar Fuel are deleted. All except solutions will be added to Small Cap. The 11 Small Cap deletions are Advanced Building Industries, Ataa Educational, Jadwa REIT Saudi Fund, Miahona, Middle East Pharmaceutical Industries, Modern Mills, Rabigh Refining & Petrochemical, Deyaar Development, Taaleem Holdings, MEEZA and Jazeera Airways. Oman India Fertiliser Company will be added to the MSCI Frontier Markets Index.
Iridium IR Brief No. 462 - What's Next for GCC Markets - 23 August 2026
The Week Ahead
Regional markets – Elusive Iran deal and UAE’s trade halt
As details emerge this week on the sanctions package described by US Treasury Secretary Scott Bessent as the “toughest sanctions in history,” negotiations with Iran will move further out of reach. The UAE’s recent halt to trade and financial transactions with Iran will prompt investor questions about exposure to Iranian customers, suppliers and payments, especially for banks, logistics firms and companies with trade links. Management teams should prepare to address counterparty exposure, sanctions screening and payment channels. A few late earnings calls are also on the agenda, including Ahli Bank, Bank Nizwa, OQ Gas Networks and Shell Oman Marketing.
Global markets – Jackson Hole, Nvidia and inflation data
Markets will focus on the Jackson Hole symposium (27-29 August), with Fed Chair Kevin Warsh’s speech the main event after the 30-year Treasury yield reached its highest level since 2007 and US debt crossed $40tn last week. Nvidia reports Q2 results on 26 August, giving investors another look at AI infrastructure demand, cloud capex and the market’s tolerance for higher financing costs. US PCE, personal income and spending, Q2 GDP and annual payroll revisions will set the tone for rate expectations. In Europe, ECB meeting accounts, Germany’s Ifo and GfK surveys, and inflation data from France and Spain are due, while Asia will focus on China’s NPC Standing Committee meeting, Japan unemployment and Tokyo CPI, and rate decisions in South Korea, Thailand and the Philippines.
Note to Management – How do higher US Treasury yields affect GCC companies?
Higher US Treasury yields affect GCC companies because dollar pegs import US monetary policy into local markets. When Treasury yields rise, the regional risk-free rate rises with them, increasing equity discount rates, debt costs and the return investors can earn from cash and fixed income. The valuation impact would be most visible in long duration sectors such as real estate, utilities, infrastructure and telecoms, as well as high dividend stocks competing with safer yields. Banks may benefit from wider margins at first, but that could fade quickly if funding costs rise, loan growth slows or asset quality weakens. Management should be ready to explain funding costs, debt maturities, capex plans and why their equity story still offers a fair return in a higher yield environment.
Iridium IR Brief No. 461 - What's Next for GCC Markets - 16 August 2026
The Week Ahead
Regional markets – Hormuz overhang and final wave of 2Q earnings calls
This week, regional markets will continue to focus on whether Hormuz negotiations can produce any visible improvement in shipping activity rather than another statement of intent. Last week’s mixed performance showed that higher oil is no longer lifting the region uniformly, as investors are distinguishing between companies supported by tighter energy and logistics markets and those exposed to slower trade, travel disruption or margin pressure. With the 2Q reporting deadline now behind us, this week should mark the final large wave of earnings calls before the calendar thins out, with 26 calls scheduled, including GFH, Industries Qatar, Jahez, Jabal Omar, Mesaieed Petrochemical, Omantel, Parkin, Warba Bank and Yalla.
Global markets – US data, Fed minutes and consumer earnings
The key question this week is whether US macro data and consumer earnings can sustain the recent equity rally, while higher energy prices keep inflation risks in view despite last week’s softer inflation report. The FOMC minutes on Wednesday will guide rate expectations after the Fed held rates in July, while US housing starts, building permits, industrial production, jobless claims and flash PMIs will show whether economic momentum is holding up. Earnings from Home Depot, Lowe’s, Target, TJX and Walmart will provide a read on consumer demand and household spending priorities. In Europe, UK labour, inflation and retail sales data, ECB meeting accounts and flash PMIs will drive rate expectations. In Asia, China activity data and loan prime rates, Japan 2Q GDP, trade, inflation and PMIs will provide the main macro drivers.
Note to Management – Saudi Arabia CMA probes IPO process
Saudi Arabia’s CMA is reportedly investigating investment banks over recent IPO performance, asking for records on pricing discussions, investor allocations and post-IPO trading activity. According to Semafor, the review follows a weak run for new issues, with several 2025 IPOs trading below offer price. The investigation turns attention to how IPOs are priced, who receives shares and what happens once trading begins. Boards preparing to IPO should expect more scrutiny on valuation, allocations and whether management is ready to engage investors immediately after the opening bell.
Iridium IR Brief No. 460 - What's Next for GCC Markets - 9 August 2026
The Week Ahead
Regional markets – Hormuz passage terms and 30 GCC earnings calls
This week, regional markets will focus on a possible arrangement to restore shipping through the Strait of Hormuz, but the reported missile attack on a UAE vessel on Saturday highlights the gap between diplomatic momentum and implementation. The proposed passage framework still faces questions over sanctions, insurance and transit fees that could limit shipowner participation, even if a deal is struck. The Saudi Arabia–Türkiye–Pakistan defence pact adds another layer to the regional security backdrop, as the three countries agreed that an attack on one would be treated as an attack on all. While markets seek answers to these questions, the 2Q earnings calendar remains busy, with 30 earnings calls scheduled this week, including ADES, Al Majed Oud, Alamar, Jazeera Airways, Kingdom, Riyad Bank, Saudi Electricity, Seera, Spinneys, Tabreed and Zain Kuwait.
Global markets – US CPI, consumer data and AI earnings
Global markets will focus on whether this week’s US inflation and consumer data confirm last week’s easing in rate hike expectations. CME FedWatch probabilities show a 44% probability of a 25bp hike at the 16 September FOMC meeting, down from 54.7% before the weaker jobs data release. CPI and PPI will be released, followed by retail sales and Michigan consumer sentiment. Applied Materials, Cisco, CoreWeave and Super Micro Computer earnings will add a read on AI, enterprise technology and cloud demand after last week’s NASDAQ rebound. In Europe, UK and Swiss 2Q GDP, Euro Area industrial production and final inflation data will guide the growth outlook. In Asia, China inflation and credit data, Taiwan GDP and the BoJ Summary of Opinions will provide the main macro insights.
Note to Management – Foreign investors trim GCC equities exposure in July
GCC equities recorded USD415mn of net foreign outflows in July, reversing June’s USD144mn inflow. Saudi Arabia saw outflows of USD129mn, ending a run of inflows in 11 of the previous 12 months. July was only the fifth time since 2019, in which all four markets recorded outflows at the same time. IR teams should identify which foreign investors reduced or exited positions, find out why they sold, and understand what would bring them back. That feedback should inform future investor meetings, 3Q messaging and guidance. Download the Foreign Flow Analysis to explore these insights in detail.
Iridium Foreign Flow Analysis - July 2026
Foreign investors trim GCC equities exposure in July
GCC equities recorded combined net foreign outflows of USD415mn in July, reversing June’s USD144mn inflow. Saudi Arabia saw outflows of USD129mn, ending a run of inflows in 11 of the previous 12 months, while the UAE was close to flat at -USD26mn (Abu Dhabi +USD148mn; Dubai –USD174mn). Outflows in Kuwait (-USD153mn) and Qatar (-USD72mn) narrowed despite renewed Iran-conflict escalation. July was only the second month this year, and the fifth since 2019, in which all four countries recorded outflows simultaneously. Year-to-date GCC net inflows remain positive at USD0.9bn.
The MSCI GCC Index fell 0.7% in July, outperforming the MSCI EM Index’s 3.3% decline. The UAE and Kuwait were the only markets to rise, gaining 1.1% and 3.3%, respectively. Their performance suggests that local investors supported individual stocks even as foreign investors reduced regional exposure.
Key takeaway for listed companies
Companies should review changes in their foreign shareholder base and identify investors who reduced or exited positions. IR teams should then prepare an engagement plan to reach out and understand why those foreign investors sold, whether they intend to continue monitoring the company, and what would need to change for them to return. These discussion should cover geopolitical risks, earnings guidance, disclosure quality and other valuation drivers. The feedback should inform engagement ahead of post-summer investor conferences and 3Q reporting.
Sources: Bloomberg, S&P Capital IQ Pro, Stock Exchanges, Iridium Advisors
Iridium IR Brief No. 459 - What's Next for GCC Markets - 2 August 2026
The Week Ahead
Regional markets – OPEC+ and 30+ earnings calls lead a busy week
OPEC+ meets today and is expected to approve a 188,000 bbl/d increase in September output quotas, completing the rollback of the 2023 voluntary cuts. The decision comes as Washington threatens further strikes on Iran, Tehran has stopped vessels attempting to leave Hormuz, and Kuwait has reported drone attacks on strategic sites. Weexpect the 2Q reporting cycle to peak with 30+ earnings calls scheduled this week, including key names like ACWA Power, ADNOC Distribution, Alpha Data, Derayah, Elm, Flynas, Luberef, Ooredoo, PureHealth, Saudi Aramco, SNB, solutions by stc and Space42.
Global markets – US labour data, AI spending and EM rate decisions to guide risk appetite
This week, US labour data will be in focus as it could reinforce the case for a September rate hike (67% probability, according to CME Fedwatch) after the Fed held rates last week with three dissenters favouring an increase. July payrolls are expected to rise by 91,000, unemployment to edge up to 4.3% and average hourly earnings to increase 0.3% MoM. JOLTS, ADP employment and ISM manufacturing and services will also provide readings on hiring, activity and prices. AMD and SpaceX earnings calls will update the AI spending outlook, where investors remain focused on capex, margins and monetisation. In Europe, German industrial production and trade data and Euro Area retail sales will update the growth outlook. In emerging markets, China’s private PMIs and trade figures, alongside rate decisions in Brazil and India, provide the main macro signals.
Note to Management – IR Impact - The risk in silence
During a geopolitical conflict such as the current one, management’s instinct is often to protect the short-term share price, limit disclosure and wait for more certainty before communicating. Investors often take a different view. They have seen similar crises play out and are less concerned with tomorrow’s share price than with whether management understands the medium-term implications for the resilience of the business model and the equity story. That distinction is important because silence, delayed reporting or strategic messaging that shifts with every news cycle can reveal more about management quality than the disruption itself. A new IR Impact feature examines “What the Gulf’s IR teams learned from war, volatility and uncertainty” (link below).
Iridium IR Brief No. 458 - What's Next for GCC Markets - 26 July 2026
The Week Ahead
Regional markets – Escalation risk shifts attention to Red Sea
The Iran conflict has widened towards Saudi territory, with Houthi attacks and Saudi retaliation increasing risk around Red Sea energy and shipping infrastructure. Brent crossed $100/bbl and Asian LNG prices reached a four-month high, keeping energy supply and shipping disruption at the heart of the regional market debate. Washington and Tehran remain in contact, but no new agreement has been reached, making any progress on safe passage through Hormuz the main potential relief catalyst this week. The corporate agenda is extremely busy, with 28 earnings calls scheduled, including Al Rajhi Bank, Alinma Bank, Aldar, Borouge, BSF, e&, Elm, SABIC and STC Kuwait.
Global markets – Fed, BoE and BoJ rate decisions and Big Tech earnings loom
It will be one of the busiest weeks of the quarter, led by Wednesday’s FOMC decision, Thursday’s US GDP and PCE releases, and results from Microsoft, Meta, Amazon and Apple. The Fed is expected to hold rates, but CME FedWatch now implies a 34% probability of a 25bp rate hike, up from 13% a week earlier, as oil above $100 revives inflation concerns. US GDP is expected to accelerate to 2.3% in 2Q, while core PCE is expected to slow to 0.1% MoM, leaving Chair Kevin Warsh to explain whether the oil shock or softer underlying inflation carries more weight. The BoE is expected to hold rates at 3.75%. In Asia, the BOJ is also expected to hold rates after June’s increase, while China’s Politburo meeting will show whether Beijing adds support as manufacturing and services PMIs stagnate.
Note to Management – Sustainability reports expand while useful evidence thins
Sustainability reports are getting longer and increasingly aligned with voluntary frameworks, while investor-useful evidence becomes more diluted. An AI review of 15,076 disclosures found that reports became less specific, less quantitative and more promotional after 2015. Around 27% of sentences were promotional, compared with 13% containing quantitative evidence and 7% disclosing negative developments. GRI, SASB and TCFD adoption produced no consistent improvement across the measures assessed. GCC management teams should assess whether investors can find material KPIs, baselines, targets, progress and setbacks, rather than judging disclosure by report length or the number of frameworks cited.
Iridium IR Brief No. 457 - What's Next for GCC Markets - 19 July 2026
The Week Ahead
Regional markets – Conflict broadens as the diplomatic exit path narrows
The week begins with the US-Iran conflict having escalated materially since last Sunday. Iran has expanded missile and drone attacks across Gulf states, two US service members were killed in Jordan, and Washington has widened strikes against Iranian targets. Commercial traffic through Hormuz has again fallen close to a standstill, while Tehran has reportedly asked the Houthis to prepare to close Bab el-Mandeb if US attacks extend to its power network. Even so, a diplomatic off-ramp remains possible if negotiations continue and both sides keep room for de-escalation. The 2Q earnings calendar also ramps up, with 24 earnings releases and 17 earnings calls scheduled for ABQK, ALRAYAN BANK, CBD, DUBK, EMIRATESNBD, ERES, IHGS, MCGS, QFBQ, QFLS, QGTS, QIBK, QIIK, QISI, QNBK, QNCD and QOIS.
Global markets – Oil prices, Big Tech earnings and ECB guidance in focus
Global investors will monitor whether the Iran conflict escalates further, with oil prices, freight costs and inflation expectations already under strain. Alphabet, Intel and Tesla earnings will test investor confidence in AI demand and semiconductor spending after last week’s technology sell-off. The ECB is expected to hold rates after its June increase, while July PMIs across the US, Europe and Asia will provide an early read on activity and cost pressures. UK inflation and employment, Japan trade and CPI complete the macro calendar.
Note to Management – Should GCC companies cut quarterly IR disclosures?
With the Iran situation absorbing a lot of management time and adding uncertainty across the region, some GCC boards are asking a fair question: “Can we ease the burden on management by cutting back on the quarterly earnings cycle?” It’s an understandable question. But for many GCC companies, especially those trying to build an institutional investor following, the answer is usually no. Reducing the frequency or depth of quarterly updates often ends up costing more than it saves. Investors notice when the flow of information slows. Their interest fades, coverage begins to thin out, and it becomes harder to win back their attention later. There are better ways to reduce the internal workload without stepping away from regular engagement. We looked at this question in detail: Link
Iridium IR Brief No. 456 - What's Next for GCC Markets - 12 July 2026
The Week Ahead
Regional markets – 2Q earnings broaden as Iran conflict escalation is back in focus
We start this week with the Strait of Hormuz back under pressure. Iran’s foreign minister met Omani mediators on Saturday to discuss vessel transit, while Washington continues to demand a public Iranian pledge that attacks stop, all lanes stay open and no tolls will be applied. Yesterday, however, Iran attacked another commercial ship and the IRGC declared the strait closed again, prompting a fresh round of US strikes. Brent gained 5.6% last week as traffic slowed sharply, keeping tanker flows, freight and insurance costs in focus. 2Q reporting continues with earnings calls expected from Dukhan Bank, Dubai Islamic Bank, Qatar Islamic Bank, QNB and WOQOD.
Global markets – US CPI and bank earnings to set the tone
Global markets enter a busy week led by US CPI, Fed Chair Warsh’s congressional testimony and the start of 2Q earnings season. US inflation is expected to slow below 4% from May’s 4.2%, while core CPI is expected to hold at 2.9%, keeping attention on whether higher oil prices are feeding into broader price pressure. BofA, Citi, GS, JPM and Wells Fargo report results, giving investors the first read on margins, credit quality, loan demand and capital markets activity. Europe’s calendar is lighter, led by UK GDP and final Euro Area inflation. In Asia, China’s 2Q GDP, trade, credit, retail sales and industrial production will show whether demand is slowing, while TSMC earnings will add a read on AI demand and Asian technology capex.
Note to Management – Quarterly reporting remains an investor confidence issue
After the SEC’s comment period on optional semi-annual reporting closed last week, investor groups urged the regulator to keep quarterly reporting. The SEC has not yet announced a timeline for next steps. The debate is highly relevant for GCC issuers because it shows how strongly investors value regular, comparable disclosure when markets face volatility, geopolitical risk and business model uncertainty. Quarterly reporting gives management teams a recurring forum to explain performance, reconcile guidance with market conditions and reduce information gaps. As 2Q reporting broadens, companies should use their earnings release, presentation and call as one connected message across margins, cash flow, funding capacity, capital allocation and 2H guidance.
Iridium IR Brief No. 455 - What's Next for GCC Markets - 5 July 2026
2Q earnings season kicks off as GCC markets reassess oil, interest rates and foreign flows
The Week Ahead
Regional markets – 2Q 2026 earnings begin as oil supply improves
The week ahead brings the first 2Q earnings read-through just as oil supply conditions begin to improve. OPEC+ meets today to decide August output targets, after Gulf oil exports recovered in June and tanker flows through Hormuz improved. Lower oil prices reduce the immediate supply-shock concern, but they also shift attention to realised volumes, pricing, margins and fiscal sensitivity across the region. The earnings cycle begins with Al Anwar Investments, Almarai, Dukhan Bank and QNB, offering investors the first management commentary since the US-Iran MOU. Saudi industrial production on Thursday will add a macro read on non-oil activity and export momentum.
Global markets – Fed minutes and services data to guide rate expectations
Global markets will focus on Fed minutes after softer US labour data and lower oil prices reduced near-term rate fears, but long-term yields remain elevated. Investors will look for how divided the FOMC was in June, how Chair Kevin Warsh frames inflation risk, and whether officials see lower energy prices as enough to pause further tightening. US ISM Services PMI, trade data, consumer inflation expectations, wholesale inventories and consumer credit will add a read on demand and price pressure. In Europe, ECB meeting accounts, Euro Area retail sales, German factory orders and industrial production will update the weak growth debate. In Asia, China inflation and Japan household spending will provide the main data input, while Delta and PepsiCo begin the early 2Q earnings cycle.
Note to Management – Foreign buyers edge back into GCC equities in June
Foreign inflows were concentrated in Saudi Arabia and Abu Dhabi. Dubai saw minor outflows while outflows in Kuwait and Qatar continue to widen since April. The US-Iran MOU and reopening of Hormuz give global investors a reason to revisit regional exposure, with the MSCI GCC Index’s (+0.4% YTD) major lag versus MSCI Emerging Markets (+19.9% YTD) adding to the argument. The 2Q 2026 reporting cycle gives management teams their first forum to quantify the impact of the conflict, explain what has normalized and demonstrate how margins, cash flow, funding and returns will be protected through year end. Download the Foreign Flow Analysis to explore these insights in detail.
Iridium Foreign Flow Analysis - June 2026
Foreign buyers edge back into GCC equities in June
GCC equities returned to net foreign inflows in June, recording USD144mn after May’s USD837mn outflow. Saudi Arabia drew USD543mn, its 11th month of inflows in the past 12 months, while the UAE returned to positive territory with USD93mn. Within the UAE, the recovery was driven by Abu Dhabi, which recorded USD120mn of inflows, while Dubai saw a much smaller outflow of USD26mn, a strong improvement from the prior three months. Outflows in Kuwait (-268mn) and Qatar (-172mn) continued to widen in June.
Year-to-date, GCC net inflows remain positive at USD1.3bn, despite the volatility around the US-Iran conflict and the closed Strait of Hormuz. Saudi Arabia remains the anchor market for foreign flows, while the UAE’s 3.3% MSCI index gain in June suggests investors are also willing to re-engage where earnings visibility supports allocation decisions.
Key takeaway for listed companies
June should be treated as the start of an allocation review. The US-Iran MOU has reopened the case for GCC allocations, while MSCI EM’s roughly 23% quarterly rally has left the region behind the broader emerging-market trade. That gap gives global investors a reason to revisit the GCC.
The 2Q 2026 reporting cycle is the first chance to demonstrate resilience after the conflict. Companies should quantify the overall impact, explain what has normalized, and show how management will protect margins, cash flow, funding and returns in the second half of the year.
Sources: Bloomberg, S&P Capital IQ Pro, Stock Exchanges, Iridium Advisors
Iridium IR Brief No. 454 - What's Next for GCC Markets - 28 June 2026
Markets turn cautious as attacks on Bahrain and two vessels renew escalation concerns
The Week Ahead
Regional markets – Iran conflict faces three possible scenarios
After the US and Iran signed an MOU on 17 June, passage through the Strait of Hormuz started to look more orderly, with traffic rising to 70-80 vessels, about 50% of pre-war traffic, and Kpler data showing c10mn barrels of oil flowing per day. Since then, a Singapore-flagged cargo ship was hit by a drone, the US struck Iranian sites in response. On Saturday, a tanker was struck in the Strait and Bahrain reported drone attacks. Brent closed at $72/bbl on Friday, down from $80/bbl a week earlier, suggesting traders still expected supply to move. Aramco’s restart of crude loadings at Ras Tanura, with two VLCCs loading, also shows producers are moving oil despite the incidents. Three scenarios are likely this week: 1) calibrated conflict, where attacks continue but the Strait stays open; 2) relief, where tanker flows improve and oil prices retreat; or 3) escalation, where further attacks or a broader US response lift oil and weigh on equities. In any case, markets will be glued to the screen as oil trading opens on Monday, but the bigger question is whether shipowners will still treat the Strait of Hormuz as passable.
Global markets – US jobs, ECB signals and Asian PMIs to guide rate expectations
US labour data and the June jobs report are due on Thursday ahead of the 4 July weekend. Consensus expects non-farm payrolls to rise by 114,000, unemployment to stay at 4.3% and wage growth to remain at 0.3% MoM. Investors will also track JOLTS job openings, ADP payrolls, factory orders and consumer confidence. In Europe, the ECB’s annual forum and June inflation data from Germany, France, Italy and Spain will guide rate expectations. In Asia, Japan’s Tankan survey and China’s PMIs will provide the main data input.
Note to Management – GCC boards must elevate value creation to earn investor trust
GCC equity markets are now predominantly driven by institutional investors who apply much higher standards than retail markets once did. Yet many listed companies continue to communicate as if they were still addressing retail investors — reporting past performance and achievements rather than explaining how they will create value over the next 3-5 years. According to Iridium CEO Oliver Schutzmann in a recent interview with the GCC Board Directors Institute, boards that have not developed a clear picture of long-term value creation will find it increasingly difficult to attract serious capital.
Should GCC companies cut quarterly IR disclosures?
With geopolitical uncertainty elevated across the region and management teams already stretched, the idea of reducing the frequency of quarterly investor relations materials can look like an attractive way to ease management workload and reduce costs. For most GCC companies, however, it is likely to prove counterproductive. Professional investors continue to value timely, structured updates. Cutting back can lead to reduced investor following and, over time, a valuation discount relative to more transparent peers.
What investors think
Institutional investors place considerable weight on the frequency and consistency of corporate disclosures. Issuers often underestimate the consequences of moving to less frequent reporting, particularly when investors must compare companies across markets, sectors and reporting regimes.
The debate has intensified following the SEC’s May 2026 proposal to allow certain companies to file semi-annual reports. While the formal comment period ended in July 2026, the proposal remains pending and no final rule has been adopted.
The SEC proposal does not change GCC reporting requirements. Quarterly financial reporting remains mandatory across the region’s main equity markets. Saudi Arabia’s Nomu parallel market is the exception, requiring only annual and semi-annual financials.
For most established GCC issuers, the immediate question concerns the voluntary IR materials that accompany mandatory financial statements, including earnings calls, earnings presentations, earnings releases and analyst data supplements. While no GCC regulator has proposed a comparable change for main-market issuers, some GCC boards are already considering cutting back these quarterly disclosures.
In June 2026 the CFA Institute, a global body that sets professional and ethical standards for the investment industry, published a survey of more than 2,500 investment professionals. Key findings included:
- 82% said that flexible reporting frequencies would make it more difficult to compare companies across their portfolios
- 74% were concerned that important information (especially negative information) would be released less promptly
- 70% opposed granting issuers broad flexibility to choose their reporting frequency
The study also found few regional differences; investors in the Americas, Europe, the Middle East, Africa and Asia held broadly similar views on the value of consistent quarterly information.
These results align with the SEC’s own Investor Advisory Committee’s recommendation to retain mandatory quarterly reporting, citing risks to transparency, wider information gaps, and an increased burden on investors.
Comment letters from the Investment Company Institute, the Securities Industry and Financial Markets Association, and Federated Hermes (writing as both a listed company and a global asset manager), similarly supported keeping the quarterly frequency, even if some less useful content could be streamlined.
Taken together, the CFA survey and institutional feedback point to a strong investor preference for regular, comparable quarterly updates.
Why the stakes are higher for GCC companies
In large, developed markets with deep research coverage and high institutional ownership, a reduction in formal filing frequency can sometimes be offset by voluntary materials. The consequences are greater where research coverage is thinner and many companies are still working to attract institutional capital.
Investors operate with a finite amount of time and attention. When information becomes less frequent or predictable, coverage often declines - especially for smaller and mid-sized companies or those that have only recently begun more professional engagement with the market. Less frequent updates slow the process of building familiarity and credibility.
Global investors apply consistent analytical standards when evaluating companies, regardless of geography. GCC companies compete for capital with regional peers and with companies in other emerging and developed markets. An issuer that reports less often requires extra work to model and compare, giving portfolio managers another reason to allocate scarce attention elsewhere. This is particularly relevant as global emerging market funds become more active in the region but remain selective about the quality and consistency of management communication as noted in our recent GCC Fund Insights.
The issuer response to the SEC proposal has been less uniform. Eli Lilly, for example, supported the proposal and indicated it expected to elect semi-annual filing while continuing to publish quarterly earnings releases. That approach may be workable for a very large, extensively covered developed market company with an established investor base and a mature reporting process. It is a less convincing model for companies that are still building international coverage and investor familiarity.
The real cost of stepping back
Quarterly reporting does impose real demands on management time and can contribute to short-term market pressure. Boards are right to examine those costs. The question is whether the savings outweigh the longer-term effects on investor engagement and valuation.
Quarterly reporting is often criticised for encouraging short-termism. While this concern is understandable, the evidence linking reporting frequency to short-termism is inconclusive. In many cases, the real drivers of short-term pressure are weak communication, overly ambitious guidance, or the lack of a long-term narrative — not the existence of quarterly updates themselves. For companies still building institutional ownership, the greater challenge usually lies in providing too little timely information rather than too much.
Companies that reduce the regularity of updates typically experience slower progress in attracting new investors, thinner research coverage, and less efficient share price discovery. These effects tend to emerge gradually and are therefore easy to underestimate.
For companies that have only recently IPO’d or launched serious investor relations efforts, the risks are more acute. Investors are still forming their views of management quality and commitment to shareholders. Reducing the frequency of engagement early in that process can quickly reverse progress that has taken time and effort to achieve. Rebuilding trust usually takes longer than maintaining it.
What message does a company send when it scales back disclosures shortly after starting to communicate more professionally? How quickly do investors reallocate attention when updates become less regular? And how long does it take to regain that attention once it has moved elsewhere?
Even if the SEC proposal is eventually adopted in the United States, it will not change investor preferences or the economics of attention and capital allocation where information gaps remain large. Companies that continue to provide regular, structured quarterly updates will stay easier to follow, model and compare.
A better alternative
Boards concerned about workload and cost should first examine how quarterly reporting is produced rather than reducing its frequency.
For most GCC companies, particularly smaller and mid-sized issuers and those seeking to build foreign institutional ownership, the preferable approach remains a full quarterly IR package. These companies already face thinner coverage, lower liquidity and fewer natural opportunities to engage investors. Quarterly reporting provides a recurring platform to explain performance, address concerns and build familiarity with management. Removing that platform would eliminate one of the few reliable tools available for increasing visibility.
Any savings in management time and preparation costs are likely to be outweighed by the effort required in attracting investors and building credibility. It also overlooks the earnings-equivalent return on investor relations.
Boards should instead focus on improving production efficiency behind the scenes. Systematic collection of quarterly data, a well-structured earnings cycle process and automated production of presentation charts and tables, can reduce preparation time from weeks to days.
These measures can support a comprehensive quarterly reporting programme without sacrificing the quality or depth of the materials investors actually need. Efficiency gains of this kind preserve the engagement benefits of quarterly reporting while addressing the legitimate cost and time pressures that boards face.
Sources: CFA Institute, SEC, Iridium Advisors
Iridium IR Brief No. 453 - What's Next for GCC Markets - 21 June 2026
Hormuz reopens as markets wait for trade flows and confidence to recover
The Week Ahead
Regional markets – Hormuz passage resumes, but caution remains
After the US–Iran MOU was signed, the Strait of Hormuz reopened and tanker traffic resumed. Oil shipments have started to recover, but flows remain below pre-conflict levels and vessels are still being asked to coordinate passage in advance. This should support risk appetite in GCC equities, although the recovery in shipping volumes, freight costs and insurance premia is likely to be gradual. Investors will also watch whether the 60-day negotiation window holds, after Saudi Arabia’s Foreign Minister warned that trust with Iran must be rebuilt before broader economic cooperation can resume.
Global markets – US PCE, PMIs and bank stress tests to guide rate expectations
Global markets will focus on US inflation, growth and banking sector signals this week. The main release will be May personal income and spending data, including the Fed’s preferred PCE inflation gauge, with core PCE expected to accelerate to 0.3% MoM from 0.2% in April. Durable goods orders are expected to fall after April’s strong increase, while preliminary S&P Global PMIs, regional Fed surveys and the third estimate of 1Q GDP will give investors a broader read on US momentum. The Fed’s 2026 bank stress test results will also be watched by financials investors. Outside the US, PMIs are due from the Euro Area, Germany, France, the UK, Japan and India, while China is expected to keep loan prime rates unchanged.
Note to Management – Investors continue to support quarterly reporting
In a letter to the SEC, the CFA Institute cited a member survey showing strong investor support for quarterly reporting. The survey found that 62% of respondents oppose replacing quarterly reporting with semi-annual reporting, while 63% believe the benefits of quarterly reporting exceed the costs. Around 70% oppose giving companies flexibility to determine or change their own reporting frequency, and nearly 85% are concerned that flexible reporting frequency and format would reduce comparability between companies. Although 82% support allowing voluntary quarterly reporting if semi-annual reporting is adopted, only 32% expect companies would continue reporting quarterly if reporting became optional. Earlier this month, the SEC’s own Investor Advisory Committee formally recommended that the SEC reject the proposal.
Iridium GEM Fund Insights - 1Q 2026
UAE and Saudi Arabia retain GEM fund allocations in a turbulent quarter
Saudi Arabia demonstrated resilience since the outbreak of the Iran war, with funds invested slightly declining to 59% during 1Q 2026 (4Q 2025: 60%) and an average fund weight of 1.19%. Fund overweight positions moderated to 10.2%.
The UAE retained its position as the most favoured GCC market, with a decline in funds invested settling at 64% (4Q 2025: 65%) and average fund weight at 1.22%. The overweight positions remained at 39%.
Real Estate and Financials maintained their leadership as the sectors with the highest fund exposure. UAE Real Estate was held by 53.3% of GEM funds, while KSA Financials were held by 50.4%.
At the individual stock level, overweight positions were led by industry leaders in the Financials and Real Estate sectors, with Emaar Properties and ADIB each recording a 1 percentage point increase in overweight positions. Aldar Properties retained the second position with a 24% overweight, followed by Al Rajhi and SNB at 20%.
Key takeaways for listed companies
Markets have swung quickly around Iran headlines, but GEM funds largely held exposure in Saudi Arabia and the UAE through 1Q. During the 1Q 26 earnings cycle, investors will focus on exposure to energy and freight costs, funding conditions, and knock-on effects on demand, margins, and working capital.
Management teams should come prepared with ranges and sensitivities, not broad statements, and be explicit on what changes in 2026 plans under different oil price and interest rate paths. Investors will ask questions on guidance assumptions, capital allocation priorities, and balance-sheet limits, and management should be available to address them directly.
Download the full report to explore the data in detail.
Sources: Copley Fund Research, Iridium Advisors Analysis
Escaping the low valuation trap
A common refrain heard in boardrooms is that our company is undervalued. Executives point to earnings growth, market expansion, and a strong balance sheet, yet the stock price remains stagnant. The assumption is often that analysts and investors are failing to see the company’s true potential, and that the market is missing something.
From a buy-side perspective, the reality is often the opposite. Many companies are not undervalued by accident - they are stuck in a pattern that limits their valuation. Institutional investors are not just looking for growth; they are looking for sustainable value creation - something that many companies struggle to demonstrate convincingly.
Why earnings growth and margins alone are not enough
For many executives, growth and margins are the ultimate measure of success. Expanding revenue, improving margins, and growing market share should, in theory, make a company more attractive to investors. Yet, time and again, companies with strong earnings trajectories fail to translate that into meaningful stock price appreciation.
The problem is that not all growth creates value. Investors are not just looking at how fast a company is growing; they are asking where that growth is coming from and whether it is generating returns above the cost of capital. A company that expands aggressively but only earns a modest return on its investments may be getting bigger, but it is not necessarily getting more valuable.
Companies that consistently attract premium valuations share a common characteristic: they generate returns on invested capital (ROIC) that exceed their cost of capital. This is the foundational metric that shows investors whether a company is creating economic value or simply recycling capital without compounding it.
A high-growth company with mediocre ROIC is unlikely to sustain its valuation premium, while a company with moderate but high-return growth is far more attractive to investors. This distinction is where many executives misread the market.
The problem with capital allocation decisions
Even companies with strong ROIC and promising growth prospects can find themselves undervalued if they misallocate capital. How a company deploys its free cash flow - whether reinvesting in high-return opportunities, making (value accretive) acquisitions, or returning cash to shareholders - has a profound impact on investor confidence.
Yet, in many companies, capital allocation decisions are often driven by tradition or influenced by large shareholder groups rather than a well-understood allocation framework. In businesses with significant family ownership, for example, the focus in boardroom discussions often shifts toward extracting capital by maximizing dividends rather than optimizing capital deployment. While dividends are important, they should not come at the expense of reinvestment when high-return opportunities exist.
From an institutional investor’s perspective, a high dividend payout can even be a red flag rather than a signal of strength. If a company is consistently returning most of its earnings to shareholders instead of reinvesting in its own growth, it signals one of two things: either the company has limited reinvestment opportunities, or management is not prioritizing long-term value creation.
Why some companies sustain their valuation premium
Institutional investors look beyond just earnings and dividends. They assess whether a company’s competitive position is defensible over time.
A company with strong ROIC today may not maintain it in the future if it lacks a sustainable competitive advantage - a moat that protects its profitability. Companies that successfully sustain their valuation premium typically have something that shields them from competition, whether it’s pricing power, brand strength, cost leadership, or regulatory advantages.
This is where many companies fail to convince investors. Their financials may look good, but investors question whether those numbers are defendable in the long run. Without a clear and well-articulated moat, even strong businesses will struggle to attract long-term investors.
The companies that get it right
A look at some of top-performing stocks reveals a pattern. These companies are not just growing, but growing in ways that reinforce their long-term value creation model.
Their success comes down to a few key factors: they maintain high and stable ROIC, they reinvest in growth areas that preserve or improve returns, they practice capital allocation discipline in word and deed, and they possess a competitive moat that protects their market position.
These companies have significantly outperformed—not because they grew the fastest, but because they grew the right way.
Breaking out of the trap
The key to escaping the low valuation trap is recognizing that investors are not only rewarding growth, but also high returns.
Executives should start by asking the right questions. Are we growing in a way that creates lasting value? Are we deploying capital efficiently, or simply expanding for the sake of it? Do we have a clear strategy for capital allocation, balancing reinvestment, acquisitions, and shareholder returns? And most importantly, can we defend our profitability in a way that protects our competitive position?
Companies that align their strategies with these investor priorities will attract the valuation premiums they seek. Those that continue to focus on growth without regard for its quality will remain frustrated by a stock price that doesn’t reflect their expectations.
Iridium Foreign Flow Analysis - May 2026
Foreign investors stay selective in May as Saudi equities attract modest inflows
May foreign flows show that investors are applying a higher risk premium to GCC equities, but they are not abandoning the region. The GCC recorded net foreign outflows of USD 837 million in May, led by selling in the UAE, Kuwait and Qatar. Saudi Arabia was the exception, with modest net inflows of USD 53 million.
Despite May’s outflow, GCC equities still recorded USD 1.1 billion of net foreign inflows year to date. The MSCI GCC Index fell 1.1% in May to 747 points and is now down 5.7% year to date from 792 points. That is a negative market reaction, but it remains relatively contained given the severity and duration of the current conflict.
Key takeaway for listed companies
Saudi Arabia’s resilience appears to reflect market liquidity, EM index weight and lower perceived energy export risk. The market offers the largest equity opportunity set in the GCC and remains the most important regional allocation for global emerging market investors. Saudi Arabia also has pipeline capacity to export crude to the Red Sea, reducing its dependence on the Strait of Hormuz relative to several GCC peers. That does not remove geopolitical risk, but it helps explain why foreign inflows have remained concentrated in Saudi Arabia.
While a peace deal appears to be making progress, investors are still waiting for proof that the crisis is moving toward a final settlement. The ceasefire has helped limit the market reaction, but the absence of a final deal continues to weigh on foreign flows. Investors will need more than headlines alone before rebuilding exposure.
Download the full report to explore the detail.
Sources: S&P Capital IQ Pro, Stock Exchanges, Iridium Advisors Analysis
GCC boards must elevate value creation to earn investor trust
Many regional boards still believe that investor trust only stems from positive announcements. That could not be further from the truth. It comes from having a value creation track record. Investors like companies that say what they are going to do and then do it. They also want management to be honest about risks that are not immediately visible to them.
GCC BDI: How are capital market dynamics in the GCC evolving, and what trends are shaping investor behaviour today?
Schutzmann: I think GCC equity markets have changed quite profoundly over the past two decades.
When I arrived in the UAE in 2006, regional markets were local markets. They were mainly influenced by domestic liquidity and retail investors. That began to change when the UAE, Qatar, Kuwait and Saudi Arabia entered the Emerging Markets indices because that brought the region into the spotlight of international institutional investors who had largely seen the GCC as a source of capital, not a destination of capital.
Over the past five years alone, we’ve seen tens of billions of US dollars in cumulative net foreign inflows into GCC markets, with Saudi Arabia and the UAE receiving the largest share.
So, this is no longer only a story about local money. The daily trading activity is now largely driven by international institutions. For instance, in FY2025, nearly 40% of traded value in Saudi Arabia was attributable to foreign institutions.
In a retail market, companies can get away with hiding behind the veil of “no comment” or PR spin in quarterly results. But in an institutional market, investors have completely different standards. They want to know if a company has growth potential, if management can generate returns in excess of the cost of capital, if management can be trusted to invest in growth and return the appropriate amount of capital, and whether management does what it promised it would do.
The last change is probably the most interesting one. The market itself is forcing GCC companies to mature. Until recently, many behaved more like private companies that happen to be listed. They engaged episodically and expected investors to work out the investment case on their own.
We are starting to see more companies look and behave like mature global companies. These developments represent meaningful progress toward the standards expected in developed markets.
GCC BDI: From your perspective, what drives investor confidence in the region’s current environment?
Schutzmann: Trust is everything. Investors need to trust the business model and the management team. That immediately becomes visible in times of distress.
When markets are relatively calm, investors can focus on growth stories, dividends and the broader regional opportunity. When there is a geopolitical shock, they will ask some really difficult questions, including: Will your business keep operating? How exposed are your margins and cash flows? How long will liquidity last? How quickly will management change its capex plans, leverage or dividends if the business landscape deteriorates further?
Many regional boards still believe that investor trust only stems from positive announcements. That could not be further from the truth. It comes from having a track record.
Investors like companies that say what they are going to do and then do it. They want management to be honest about risks that are not immediately visible to them. They dislike broad reassurances because the chances are that investors have seen a similar playbook somewhere else and know how that ends.
That is why many companies lose investor trust when they delay bad news, react like a deer in the headlights to every headline, and try to manage their daily share price with positive statements. That creates the impression that management is not in control.
Companies that build trust do the opposite. They engage early, use public forums like analyst calls to explain the decisions they are making, they highlight the risks and demonstrate how the business will endure longer periods of volatility.
GCC BDI: How should boards position their organisations to remain attractive to both regional and international investors?
Schutzmann: I think boards need to hold up a mirror and ask a simple question. Would an investor understand why this company deserves their money if they looked at it for the first time?
Many companies in the region have fundamentally strong businesses, but they don’t always know how to translate that strength into a convincing investment case. They report quarterly results, announce strategic milestones after they already met, but they wrestle with explaining long-term value creation and painting an accurate picture of where the business will be in 5 or 10 years.
For boards that means capital markets positioning has to go beyond regulatory disclosures. The most advanced GCC companies, for example Saudi banks, give investors a framework. They portray an accurate picture of the bank in the future, explain their strategic, financial and operational roadmap and report detailed progress every quarter. That allows investors to confirm or discredit their investment thesis.
Boards should position their organisations as companies that can be understood, measured and trusted over time. That is what ultimately attracts both regional and international capital. That is why mature public companies do not treat investor engagement merely as a marketing function when the sky is blue. The board, CEO, CFO, IR team and broader management also need to have the same view of the market’s expectations when the sky is grey.
GCC BDI: Looking ahead, what should boards prioritise to strengthen their capital markets narrative and access to investors?
Schutzmann: Based on conversations with company leadership and investors, I believe GCC boards would benefit from spending more time understanding who and what really drives their share price.
That starts with an outside-in perspective. Many boards still operate with outdated assumptions about what investors expect.
Some believe that earnings guidance is not allowed, even though all public Saudi banks now provide guidance. Others remain hesitant on strategy disclosure because they believe they will give away their competitive advantage. Many others still see no need for quarterly earnings calls, although the number of GCC earnings calls has risen from fewer than 10 companies a decade ago to more than 130 per quarter today, representing around 80% of total GCC market capitalization.
However, the deeper challenge is that many boards still look at the company mainly through the P&L, while institutional investors look at cash flows, moat and capital allocation. For example, many companies don’t seem to look at whether they consistently generate returns above their cost of capital. Only a few companies publish a dividend policy, not to mention a capital allocation policy.
Therefore, the priority needs to be to move from reporting activity to explaining value creation. Investors do not need a laundry list of everything the company is doing. They want to know the three or four key things that will make returns sustainable, where growth will come from, how capital will be used, and what management will do if market conditions change.
Valuation is ultimately the product of business model performance and trust in management capability.
What role does governance play in influencing valuation, transparency and long-term investor trust?
Governance is fundamental because it tells investors how a company will behave when tough decisions need to be made. Quite often, governance can sound like a compliance topic, but investors see it differently. They are trying to assess if the board will protect minority shareholders, if capital will be allocated responsibly, and whether management will be held accountable. If they have doubts on any of those points, they will either demand a lower valuation or could avoid the company altogether.
Transparency is part of the same equation. A well-governed company not only publishes more information, but also information that helps investors make buy, sell or hold decisions. That means consistent KPIs, explanations of what drove and held back performance, and enough forward-looking context to understand where management sees the business in 3-5 years.
Is Investor Relations a Front Office or Back Office Function?
Investor Relations often finds itself stuck in an identity crisis. Is it a compliance-driven back-office function, similar to accounting, tasked with disclosure and reporting? Or is it a strategic, market-facing role that actively drives shareholder value, placing it alongside front-office activities like sales or corporate strategy? The truth lies in IR’s core objective: to shape how capital markets perceive and value a company.
The question whether IR is a front office or back office function has implications for how companies deploy resources, define priorities, and measure their success. The key lies in recognizing IR’s unique ability to match a company’s performance with the capital market’s perception—an interplay that is central to value creation. Getting it wrong risks diminishing the value that IR can create for the company, its owners, and its management.
Investor Relations' Misunderstood Role
For many years, IR was seen as a function focused on reacting to market needs—preparing earnings reports, managing disclosure, and arranging annual general meetings. While these activities are important, they do not capture the transformative potential of IR in today’s complex capital markets. This compliance-first approach relegates IR to the sidelines, denying it the resources and authority to shape the company’s investment narrative proactively.
At its core, IR serves as the voice of the company to investors, analysts, and the broader market. This role has evolved substantially, driven by rising investor demands for transparency, the growing influence of ESG factors, increased scrutiny from institutional investors, and the increasing role of AI in the investment process. Modern IR is not merely about disseminating information; it is about shaping the company narrative. This means conveying how performance aligns with market expectations and, in doing so, influencing valuation multiples.
The Bridge Between Performance and Perception
To understand why IR deserves to be considered a front-office function, it is necessary to break down its role into two pillars: performance and perception. These pillars are not merely distinct areas of focus; they represent the interplay that ultimately determines a company’s valuation in the market.
Performance is the foundation of measurable operational and financial outcomes. Institutional investors look for companies with compelling strategies, disciplined capital allocation, and strong returns above the cost of capital. IR plays a central role in articulating these metrics to investors. For example, it demonstrates how a company is positioned in its industry, where its growth will come from, and how resources are being deployed to create value sustainably. Without IR translating these fundamentals into a cohesive narrative, the market risks undervaluing the company’s achievements.
Perception, on the other hand, is the multiplier effect. While performance builds the foundation, perception determines the valuation premium (or discount) that the market applies to a company. Investors trust companies with credible management teams that deliver on their promises and engage transparently. A mature IR function not only engages proactively with stakeholders but also articulates external expectations inside the company Together, these pillars of performance and perception define a company’s market valuation.
Earnings Equivalent Valuation Premium
Let’s take an example of an airline. The company trades at a P/E ratio of 10.4x, based on net income of USD 1.38 billion, giving it a market capitalization of approximately USD 14 billion. A more mature front office IR function which understands what information investors need, how they come to their valuations, and effectively communicates corporate strategy and capital allocation could potentially generate a valuation premium and improve the airline’s P/E ratio by around 15%, from 10.4x to 12x.
Key insight: IR can provide a far more efficient lever for value creation than operational improvements alone. A 15% improvement in P/E ratio through stronger market perception is equivalent to a 13.9% revenue increase—without adding a single dollar in operations.
The resulting valuation uplift would increase the airline’s market capitalization by USD 2.1 billion, a figure too big to be ignored in discussions of value creation by executives and the board. To achieve this hypothetical USD 2.1 billion uplift through operational improvements alone, the airline would need to grow its net income by USD 215 million. Given the company’s FY2023 net income margin of 25.8%, this would require an additional USD 833 million in FY2023 total revenue – or the equivalent of a 13.9% annual revenue increase. Achieving such growth in a highly competitive industry, where margins are constantly under pressure, would be far from easy.
{{statistics}}
This scenario highlights the outsized impact that IR’s ability to improve market perception can have on valuation. While operational performance will always remain the foundation, IR can provide a highly efficient lever for value creation. By positioning IR as a front-office function, companies like the airline example can unlock valuation premia, drive shareholder confidence, and achieve outcomes that would otherwise demand significant - perhaps impossible - operational improvements.
Designating IR as Front Office
Treating IR as a front-office function changes how the organisation creates value. It gives IR a strategic mandate, closer proximity to leadership and direct accountability for helping management understand and influence valuation outcomes. Companies that fail to recognize this strategic importance are leaving untapped value on the table.
When IR is seen as a strategic partner, its insights on market sentiment, investor expectations, and valuation drivers are not just heard but can proactively influence corporate strategy.
The capital markets reward companies with proactive IR functions. For investors, it signals that the company understands its audience and takes its market-facing responsibilities seriously. Internally, this shift elevates IR’s role, ensuring it is equipped with the resources, tools, and authority to make a meaningful impact on valuation.
Reimagining IR in Organizational Design
For IR to operate effectively as a front-office function, companies need to embed it more deeply into their organizational design. This means granting IR a seat at the table where strategic decisions are made and making it accountable for delivering insights that drive valuation.
A well-structured IR function should report directly to the CEO or CFO and have representation in executive committee discussions. This proximity allows IR to translate investor expectations into actionable insights for leadership, while also ensuring that corporate decisions are communicated effectively to the market. Regular internal board reporting - covering market sentiment, valuation analysis, and investor engagement metrics – then ensure IR’s contribution is recognized and informs strategic planning.
Next to finance, IR must also integrate with other key functions, such as strategy, business lines, and ESG. As ESG concerns grow, IR’s role in articulating the company’s sustainability narrative becomes critical. This collaboration ensures that the company’s story resonates with the expectations of long-term investors, who increasingly prioritize these non-financial factors.
The Broader Implications for Companies
Designating IR as a front-office function also changes how companies measure and reward its success. Instead of focusing solely on disclosure accuracy or internal feedback, companies should evaluate IR’s impact on valuation. This better reflects IR’s strategic contribution and aligns with its role as a pillar of shareholder value creation.
The benefits of the shift are obvious. Companies that treat IR as a strategic, market-facing role tend to attract long-term, stable investors and achieve higher valuation premiums. By proactively managing the investment narrative and aligning external with internal expectations, these companies are also better equipped to meet sell-side analyst forecasts and buy-side expectations.